The Analyst Parade: $1,200, $1,250, and Even $3,000?
Wall Street is falling over itself to raise targets. Evercore ISI just initiated coverage with an “Outperform” rating and a $1,200 price target, noting SanDisk is “connected to the most attractive AI infrastructure data storage sector”. In a bull-case scenario, Evercore sees the stock hitting $2,600.
Bernstein went even further, raising its target from $1,000 to $1,250 and naming SanDisk its top short-term pick. Analyst Mark Newman argues the market is “significantly undervaluing SanDisk’s earnings power and sustainability of this cycle”. In his “blue-sky” scenario, he laid out a $3,000 valuation—implying roughly 250% upside from current levels. Jefferies also jumped in, raising its target from $700 to $1,000 while maintaining a Buy rating.
The valuation math is compelling. SanDisk currently trades at just 9x forward earnings—well below the 10–13x range during prior upcycles, and at only half the Philadelphia Semiconductor Index’s multiple. Meanwhile, forward P/E is expected to compress to roughly 10x next year as earnings continue accelerating.
The Bear Case: Gravity Hasn’t Been Canceled
This Is Still a Cyclical Business
As exciting as the AI story is, NAND flash memory remains one of the most notoriously cyclical industries on the planet. The industry has a long history of brutal boom-bust cycles where downturns in pricing can quickly sink margins—and stock prices. The last crash happened in 2023, when major memory producers all posted annual operating losses.
Today’s record margins are heavily driven by surging NAND contract prices, which have risen dramatically. While the outlook remains positive, any shift in supply discipline—say, if competitors suddenly decide to ramp production—could rapidly erode pricing power and profitability. Some analysts have already raised caution flags about NAND prices potentially peaking.
Profit-Taking Is Real
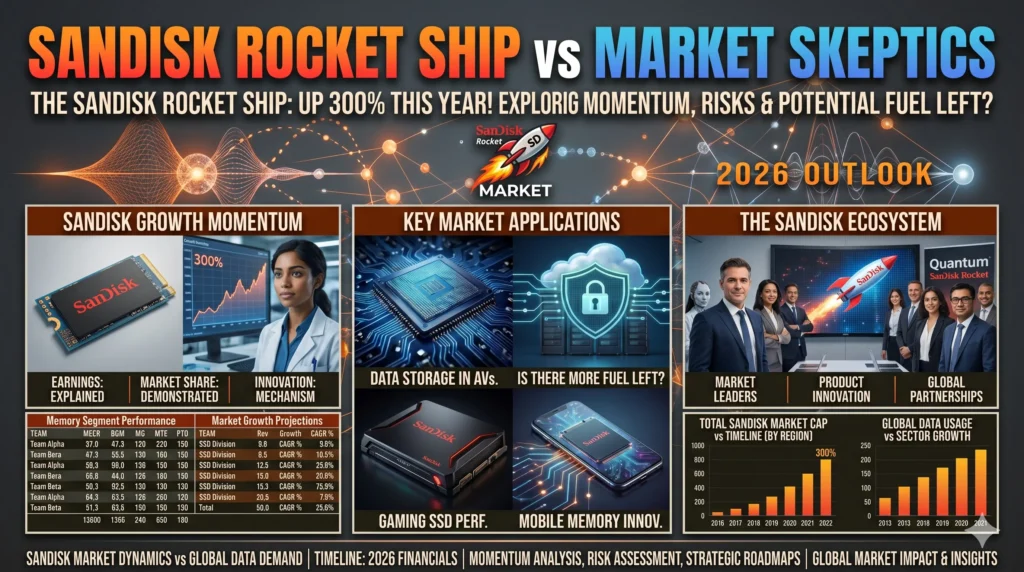
When a stock is up 301% year-to-date, some profit-taking is not just possible—it’s almost inevitable. Even the most bullish analysts acknowledge the recent volatility as a “healthy correction” given the magnitude of the move. Lower trading volumes during certain periods can amplify downward moves during sector rotations, making the stock susceptible to sharp pullbacks.
The Google TurboQuant Episode
Remember what happened just weeks ago? When Google unveiled TurboQuant—a memory-compression algorithm—the stock pulled back roughly 19% on fears that it could weaken NAND demand. Bernstein ultimately argued those fears were “overdone,” noting the technology primarily targets high-bandwidth memory for AI inference with limited bearing on NAND’s broader storage role. But the episode serves as a reminder: in this hyper-sensitive market, even unproven technological developments can trigger double-digit selloffs.
What to Watch Next
April 30, 2026 is the next major milestone. That’s when SanDisk reports its fiscal Q3 results, offering the first real test of whether the company can actually deliver on its massive guidance. The stock is pricing in perfection at these levels, and as several semiconductor names have shown recently, even strong quarterly results can trigger muted or negative reactions when valuations leave little room for disappointment.
The Kioxia joint venture extension through 2034 secures long-term manufacturing capacity, but it also comes with a $1.165 billion payment obligation between 2026 and 2029. And while the Nasdaq-100 inclusion is great for visibility, it also means the stock will be subject to the same sector rotations that affect every other index heavyweight.
The Bottom Line
SanDisk has transformed from a sleepy spin-off into arguably the hottest AI infrastructure play in the market today. The combination of explosive earnings growth, structural supply constraints through 2028, and now Nasdaq-100 inclusion creates a compelling narrative. The stock’s valuation—trading at a discount to historical cycles and to its semiconductor peers—suggests there could be more room to run.
But a 301% year-to-date gain doesn’t come without risks. This is still a cyclical memory business, and the higher the stock climbs, the harder it falls when sentiment shifts. The April 30 earnings report will be the moment of truth.
One thing is certain: whether you’re bullish or bearish, SanDisk is impossible to ignore right now. And in today’s AI-driven market, that might just be the point.